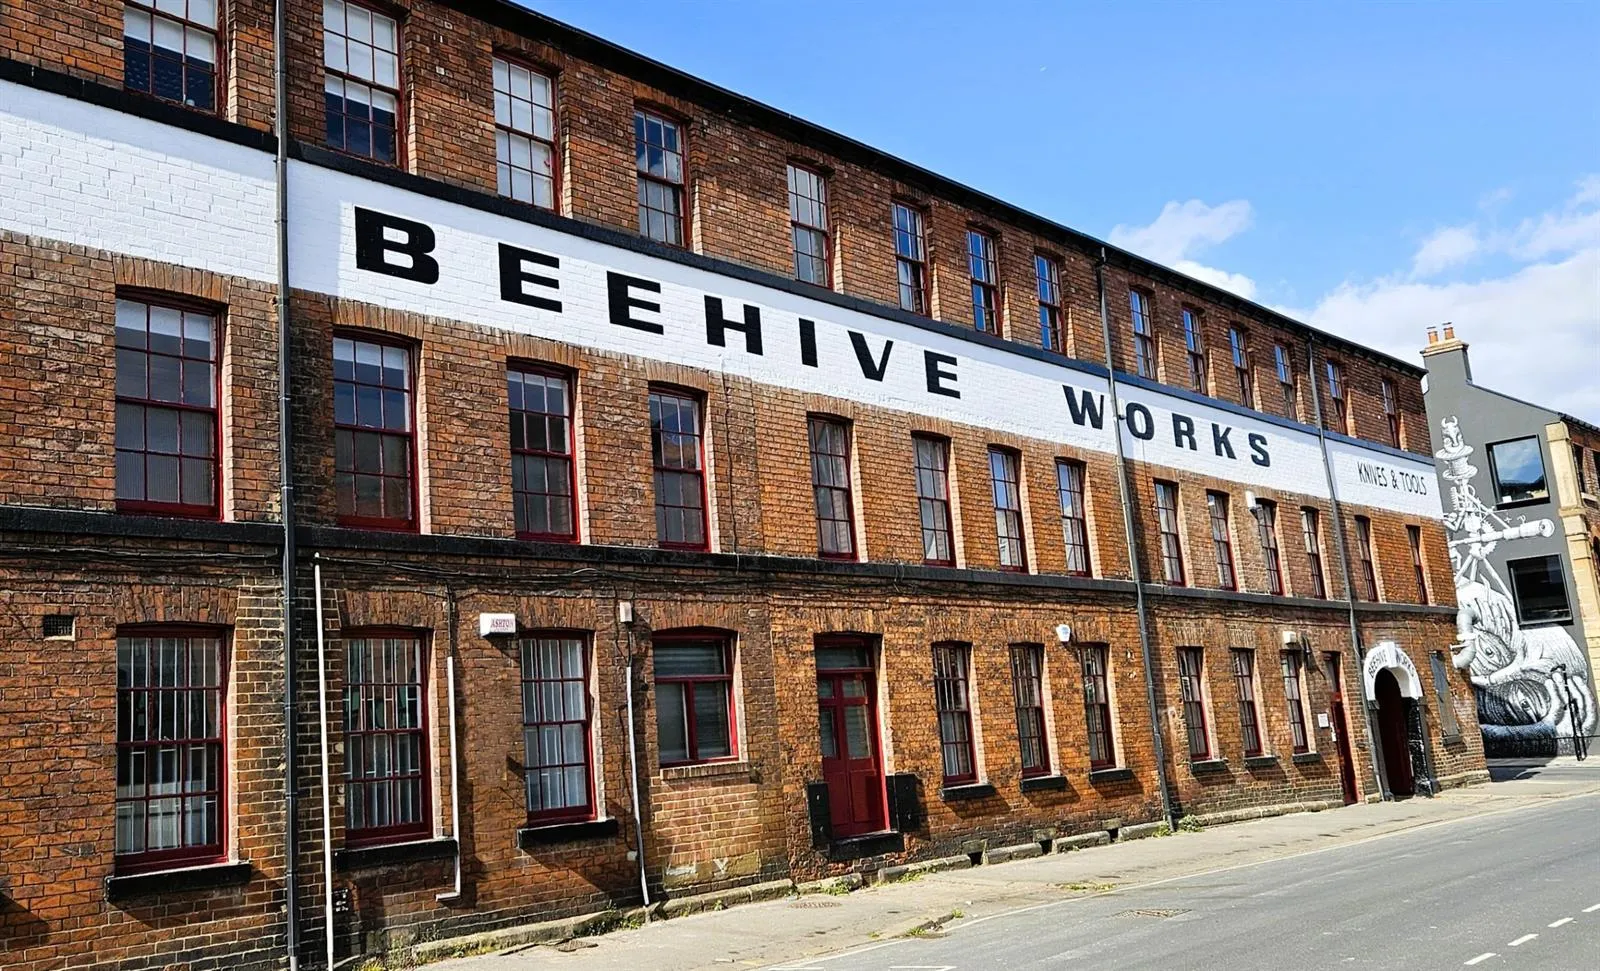
Friends Capital is an FCA-regulated, whole-of-market mortgage broker based at Beehive Works in Sheffield, on the edge of the Peak District. We help buyers and homeowners across the Peak District and in Chesterfield, including people buying homes that many lenders find harder to deal with, such as properties with local occupancy restrictions. You can speak to us by phone, by video or at our Sheffield office.
House prices vary more across this area than almost anywhere nearby. Homes in the Derbyshire Dales cost well above the national average, while Chesterfield is one of the more affordable towns in the region.
Source: HM Land Registry UK House Price Index, July 2026 (the latest figures available). Averages hide a wide range; your home's value depends on its size, type and location.
What that means in practice: a first-time buyer paying the Derbyshire Dales average of about £286,700, with a 10% deposit, would need a mortgage of around £258,000. At 4.5 times income, that takes a household income of about £57,300. In Chesterfield, the same calculation needs about £35,500. That gap is one reason so many Peak District homes are reserved for local people.
Many homes in the Peak District are perfectly straightforward to mortgage. But some have features that rule out a lot of lenders, and it pays to know before you make an offer.
We'll check how lenders view the property before you commit, so there are no surprises late in the process.
From Sheffield's western edge, where the National Park begins, we help clients buying across the Peak District: in the Hope Valley and Hathersage; in Bakewell, Matlock and Ashbourne in the Derbyshire Dales; and in Buxton, Glossop and Chapel-en-le-Frith in the High Peak.
Prices here are high. The Derbyshire Dales average is £355,387, about £62,000 above the England average, and prices rose 7.1% over the year. High Peak averages £258,856. Many of our Peak District clients work in Sheffield, and the Hope Valley railway line connects the two.
The Peak District is one of the most popular places in the UK for holiday lets, and we arrange many holiday let mortgages for clients buying here. They work differently from a standard buy-to-let:
Read our full guide to holiday let mortgages.
Letting on a long-term tenancy instead? See our buy-to-let mortgages page.
Most holiday let mortgages are not regulated by the Financial Conduct Authority. Your property may be repossessed if you do not keep up repayments on your mortgage.
Chesterfield is just south of Sheffield, and we help buyers and homeowners across the town and its surrounding areas, from Brampton and Walton to Newbold, Brimington, Hasland and Staveley.
Chesterfield's average house price is £203,367, about £90,000 below the England average, and first-time buyers pay an average of £177,738. With fast trains to Sheffield, it's a popular choice for buyers who work in the city but want more for their money.
For homes in Sheffield, including Dronfield and the villages on the city's southern edge, see our mortgage advisers in Sheffield page. For Rotherham, Barnsley and Doncaster, see our South Yorkshire page.
We arrange mortgages for clients across the Peak District and Derbyshire in every situation, including:
Your home may be repossessed if you do not keep up repayments on your mortgage.
Our team includes Robert Wilson-Rust (Senior Mortgage and Protection Adviser), Tiffany Taylor and Katie Stoker (Mortgage and Protection Advisers), all CeMAP qualified, and Ceri Walby (Mortgage Case Manager), who looks after your application through to completion.
Common questions about mortgage advice in the Peak District and Derbyshire.
Can you arrange a mortgage on a home with a local occupancy restriction?
Often, yes. Fewer lenders will consider homes with a local occupancy restriction, and some will want a larger deposit, but there are lenders that do. We'll check whether you meet the occupancy conditions and find a lender that accepts them before you make an offer.
Will buying in the Peak District limit which lenders I can use?
Not usually. Most homes in the Peak District can be mortgaged in the normal way. Restrictions such as local occupancy or agricultural ties, and features such as private drainage or land, can narrow the choice, and we'll tell you how lenders view the property before you commit.
Do you cover Chesterfield?
Yes. We help buyers and homeowners across Chesterfield and the surrounding areas, as well as in the Peak District, Sheffield and South Yorkshire.
Do I need to come to your Sheffield office?
No. Most clients speak to us by phone or video call and send their documents securely online. You're also welcome to meet us at Beehive Works in Sheffield if you prefer.
Are house prices higher in the Peak District?
Yes, in many areas. In July 2026 the average price in the Derbyshire Dales was £355,387 and in High Peak £258,856, compared with £293,479 across England and £203,367 in Chesterfield, according to HM Land Registry.
Do you arrange holiday let mortgages?
Yes. We arrange many holiday let mortgages, particularly in the Peak District. Lenders usually base the loan on the expected holiday letting income and want a deposit of at least 25%. We'll check the property's planning position before you commit.
Reviewed by Zoe White CeMAP, Compliance Officer, Friends Capital. Last reviewed October 2026.
Wondering what we charge? Your initial consultations and discussions are free, and our mortgage fee is typically £795 — most of it payable only on completion. See our fees in full.